Parent Boost Visa New Zealand: can the family sustain a long visit?
Visa guide · 2026-10-18 · 7 min read
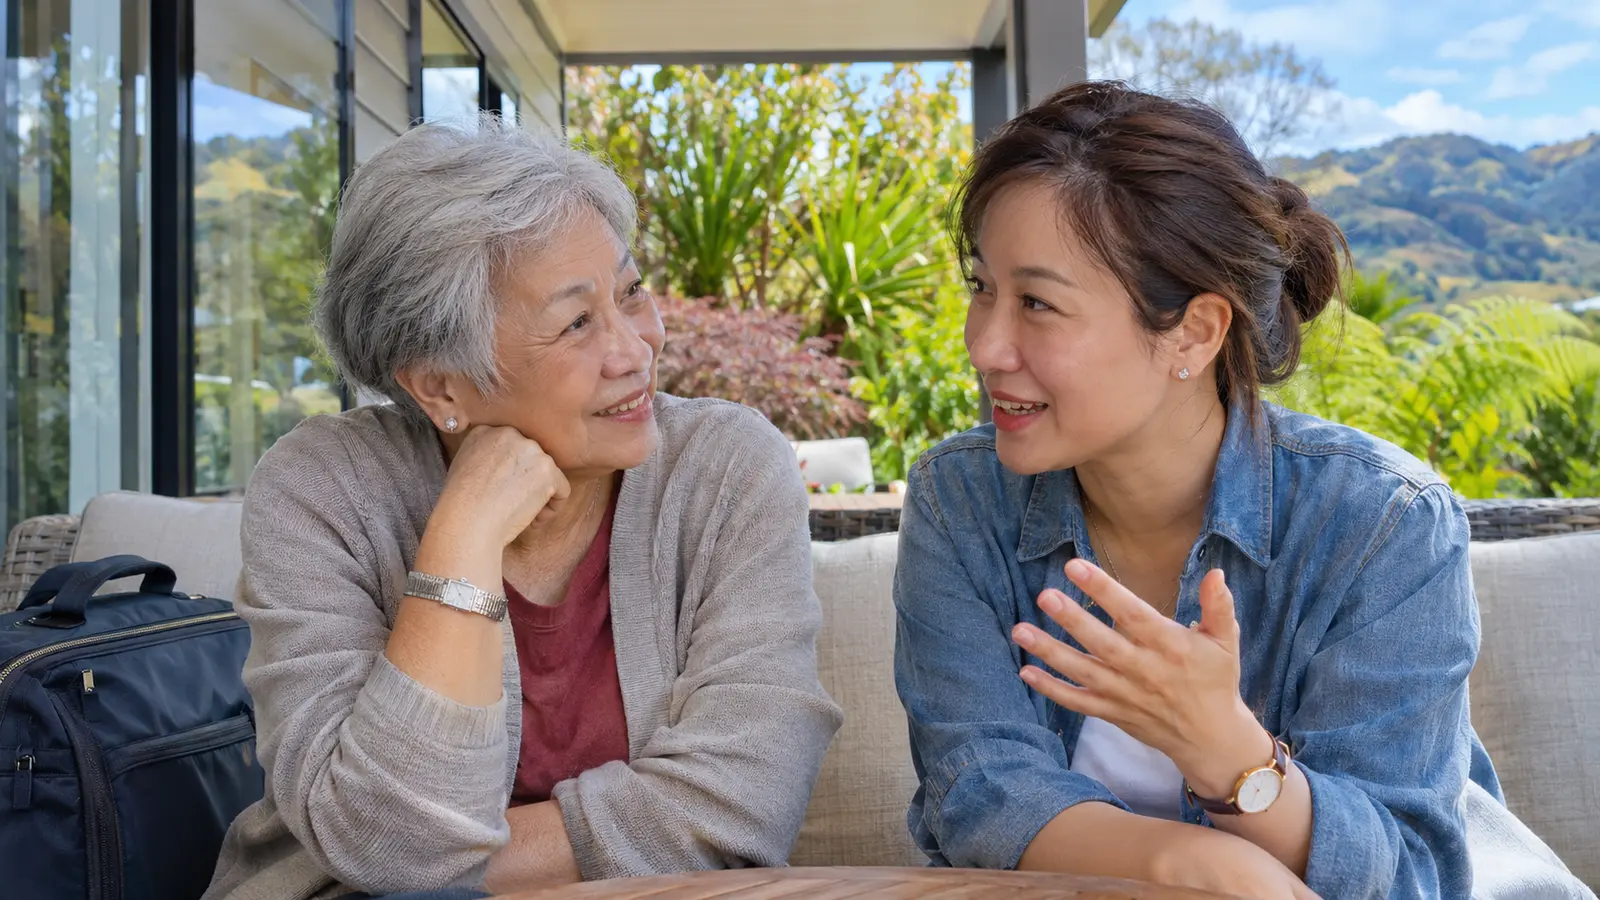
The Parent Boost Visa New Zealand offers can support a longer family visit, but duration is only one part of the decision. The family also needs a financial basis, suitable insurance and a plan for later checks. Treating the application as a one-off travel purchase can leave important obligations out of view.
The Parent Boost Visitor Visa opened for applications on 29 September 2025. It is a visitor arrangement, not a pathway to residence. Start the discussion by asking what kind of visit the family wants and whether the relevant income, funds and insurance conditions fit that plan.
Parent Boost Visa New Zealand: decide what the visit is for
The visa is multi-entry and can last up to five years. A second five-year visa is possible, giving a potential total of up to ten years. That does not make the first application an automatic ten-year permission, and it does not convert the visitor arrangement into residence.
The listed visa cost starts at NZ$3,100, with processing taking around four months. Keep both descriptions qualified: a starting cost is not every household expense, and an approximate processing time is not a personal completion deadline. Read the Parent Boost Visitor Visa conditions before building commitments around an assumed result.
Discuss the practical purpose of the visit with the parent, rather than viewing it only through the adult child's needs. Consider the living arrangement and how family members will manage time together. These are household planning questions, not additional immigration conditions.
Keep any work or residence ambitions separate from the visitor plan. Do not assume that living near a working adult child gives the parent the same immigration status. A long visit and a permanent move need different decisions.
Choose the financial route that matches the evidence
From 30 April 2026, a single sponsoring adult child who is a New Zealand citizen or resident needs income of NZ$72,800 to sponsor one parent, or NZ$109,200 for two. Keep the sponsor's citizenship or residence condition visible instead of extending it to every temporary worker living in New Zealand.
Parents may instead show annual income of NZ$33,663.24, or NZ$51,182.56 with a partner. The listed funds alternative is NZ$170,000, or NZ$260,000 with a partner. These are specific financial options, rather than amounts that can be freely substituted into another visa category.
| Verified financial option | One parent or single parent applicant | Two parents or parent with partner |
|---|---|---|
| Single sponsoring adult child's income, from 30 April 2026 | NZ$72,800 | NZ$109,200 |
| Parents' own annual income | NZ$33,663.24 | NZ$51,182.56 |
| Parents' funds | NZ$170,000 | NZ$260,000 |
The dated income-threshold update provides the basis for these amounts. Confirm which option you are using before collecting evidence, and keep the period and the people covered by each amount clear.
Meeting a listed financial threshold does not complete every condition of the visa. It also does not establish that the household has budgeted comfortably for the visit. Keep the immigration evidence calculation separate from a practical discussion about ongoing expenses.
Read insurance by coverage category rather than policy name
Parent Boost applicants need medical and travel insurance covering at least NZ$250,000 a year for emergency care and NZ$100,000 a year for cancer cover. The minimums also include NZ$250,000 for repatriation and NZ$50,000 for return of remains.
Those categories deserve careful attention even when the conversation is uncomfortable. A policy described broadly as comprehensive travel cover does not establish that every required amount is included. Compare the actual policy wording with the visa requirements.
Record any question you need the insurer to answer, and retain the answer with the policy. Do not replace an unresolved coverage question with an assumption that it will probably be accepted. The objective is to understand the cover the parent actually has.
Our account of health questions in a family migration case explains why another household's circumstances cannot decide an individual assessment. It should not be used to infer an exception to Parent Boost insurance requirements.
Put the third-year check on the family calendar
The visa includes a health and insurance check during the third year. Build that checkpoint into the plan from the outset instead of treating the initial grant as the last administrative task. Identify who will keep the records organised and who will follow up when a question arises.
A shared folder can hold the visa decision, insurance information and correspondence relevant to future checks. Keep the actual documents accessible to the parent as well as the adult child. Organising records is practical preparation; it should not be confused with adding a new formal requirement.
Review the household arrangement as circumstances change. A longer visit may involve changes in accommodation or family routines. Do not assume that meeting an initial financial figure answers every practical question over the full period.
Keep Parent Resident research on a different page
The Parent Resident Visa is a different category, with a listed starting cost of NZ$5,810 and 2,500 places a year. Those figures should not be added to the Parent Boost permission or treated as evidence that a visitor can move automatically into residence.
If the family's real goal is permanent settlement, identify the relevant residence requirements directly. Parent Boost's potential duration may be attractive for a visit, but calling it a residence pathway changes what the category provides.
The same discipline applies when comparing Australia as another destination. Our coverage of Australian parent visa timing concerns a separate system. An Australian waiting discussion does not establish the New Zealand parent's eligibility or processing date.
Discuss the household plan without assuming an outcome
Write down where the parent expects to stay and what support the family has actually agreed to provide. Separate a willingness to help from a confirmed arrangement. If the plan relies on a future change in employment or housing, identify that dependency before committing to travel.
Our article on returning families and household costs raises related budgeting questions. It does not set Parent Boost eligibility, but it can help a family discuss costs with more precision.
Use our visa guides to organise the category research. If an adult child is also considering a career change, read actual job requirements separately; a possible future role is not existing income evidence.
Work through the decision in a sensible order
- Agree whether the aim is an extended visit or permanent settlement.
- Confirm the sponsoring adult child's relevant citizenship or residence status.
- Identify the financial option and the people covered by it.
- Check every insurance category and minimum against the policy.
- Allow for processing without treating an estimate as a fixed date.
- Plan for the third-year health and insurance check.
Common mistakes in a long family-visit plan
Avoid describing Parent Boost as residence, promising ten years from the first application or assuming every New Zealand-based child can sponsor under the same conditions. Do not compare policies only by price while leaving the coverage categories unread. Keep the later health and insurance check visible in the family's plan.
Frequently asked questions
Is Parent Boost a residence visa?
Parent Boost is a visitor visa and is not a pathway to residence. A long permitted visit should not be described as permanent settlement.
Does the first Parent Boost visa allow ten years automatically?
The first visa can last up to five years. A second five-year visa is possible, bringing the potential total to ten years, rather than making ten years automatic.
Can parents show their own income or funds?
The verified financial options include specified parent income or funds as alternatives to the sponsoring child's income. Check the relevant option and whether a partner is included.
Is ordinary travel insurance enough for Parent Boost?
The policy needs to meet the specified medical and travel insurance minimums. Check each coverage category rather than assuming a general policy is suitable.
What needs attention in the third year?
Parent Boost requires a health and insurance check during the third year. Include that checkpoint in the family's ongoing plan instead of focusing only on the initial application.
Key takeaways
- Parent Boost supports visits rather than a pathway to residence.
- Distinguish the first visa from a possible second application.
- Use the correct financial option and dated thresholds.
- Read each insurance minimum carefully.
- Prepare for the third-year check from the start.
Last checked: 18 October 2026 against the official pages linked above.
To discuss the family's immigration options, book a consultation with licensed immigration advisers in New Zealand or lawfully exempt professionals.
#parent boost visa new zealand #parent boost visitor visa #family visits new zealand #parent visa insurance #parent boost income #new zealand parents
 Australia employer sponsored visa 2026: will the offer support the next step?
 Overseas plumber registration in New Zealand: could you start restricted work too soon?
 National Occupation List New Zealand: could the wrong code distort your whole work plan?